

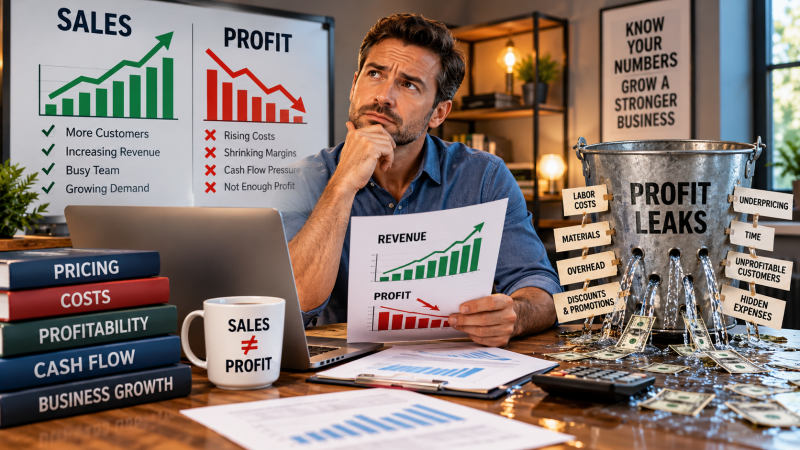
You’re bringing in customers, making sales, and staying busy. So why does it feel like there’s never enough money left over? Let’s break down the difference between generating revenue and building a genuinely profitable business—and how to find the money your business might be leaving on the table.
Let’s talk about something that doesn’t get nearly enough attention in the small business world.
You can have a busy business, a growing customer base, and impressive sales numbers and still struggle to make a decent living.
Think about that for a moment.
You’re answering calls, responding to emails, managing projects, delivering products, keeping customers happy, and doing everything you can to grow your business. Your calendar is full. Your inbox never stops filling up. Money is coming through the door.
From the outside, everything looks great.
But when the bills are paid, your employees have been compensated, your suppliers have received their money, and you’ve covered your operating expenses, you’re left wondering where all that money went.
Maybe you’re even working harder than you were six months ago, serving more customers than ever before, and somehow finding yourself in a worse financial position.
If that sounds familiar, I want you to understand something important.
Your business might not have a sales problem. It might have a profitability problem.
And those are two very different challenges requiring two very different solutions.
I’m a big believer in helping business owners understand how to grow their businesses strategically. But sustainable growth isn’t just about getting more leads, reaching more people, or convincing more customers to buy your products and services.
It’s also about understanding your numbers, protecting your margins, and making sure the work you’re doing is actually contributing to your bottom line.
Because what’s the point of growing a business that generates more revenue every month if that growth leaves you with more expenses, more stress, and barely any additional profit?
Let’s break this down, look at where your money might be going, and walk through a practical process you can use to identify opportunities to improve your business’s financial health.
Revenue Isn’t Profit. Let’s Stop Treating Them Like They’re the Same Thing.
One of the biggest mistakes I see business owners make is confusing revenue with profitability.
It’s an easy mistake to make, especially when you’re constantly focused on growing your customer base and increasing sales.
Revenue is exciting. It’s easy to measure, easy to celebrate, and easy to use as a benchmark when comparing your business to competitors.
But revenue only tells you how much money your business generates from its sales. It doesn’t tell you how much money you actually get to keep.
Let’s say you own a small service business that generates $25,000 in monthly revenue.
That’s $300,000 in annual revenue.
Sounds pretty good, right?
Now let’s look at what happens when we start accounting for the costs of running that business.
Where Does Your Business Revenue Go?
A practical look at how revenue, expenses, and operating profit work together. Explore the monthly figures to see why generating more sales doesn't always mean keeping more money.
Monthly Financial Performance
Explore Each Month
January Financial Breakdown
Where the Money Goes
In this simplified example, the business generates $25,000 in monthly revenue but has $6,500 remaining after the listed expenses.
That’s an operating margin of 26%.
However, this example assumes the business has accounted for all relevant operating expenses within those categories. Depending on the business, additional expenses may include owner compensation, depreciation, interest, taxes, and other costs that would change the final result.
The important lesson isn’t the specific margin.
It’s the difference between the money coming in and the money the business actually retains.
Now imagine that the owner sees an opportunity to double monthly revenue from $25,000 to $50,000.
Naturally, that sounds like a fantastic opportunity.
But what happens if doubling revenue requires twice as much labor, additional equipment, more advertising, additional insurance, and an expensive new vehicle?
Revenue might double while profit barely improves.
In some cases, profit can actually decline.
This is why the distinction matters so much.
The Internal Revenue Service explains this distinction in its Tax Guide for Small Business, which outlines how businesses calculate gross profit after accounting for applicable sales adjustments and the cost of goods sold.
Gross profit, operating profit, and net profit are different measures, and understanding what each one includes is essential to making informed decisions.
Here’s a simple way to think about it:
- Revenue: How much money your business generates through sales.
- Gross profit: What’s left after subtracting the direct costs associated with producing or delivering what you sell.
- Operating profit: What’s left after accounting for operating expenses, before interest and taxes under the conventional operating-profit definition.
- Net profit: What’s left after accounting for the expenses included in your income statement, including applicable interest and taxes.
Your exact financial statements may present these figures differently depending on your business structure and accounting method.
But the principle remains the same.
Sales tell you how much business you’re doing. Profit tells you whether that business is financially rewarding.
And you need to understand both.
The Hidden Costs of Serving Your Customers
Here’s where things get interesting.
A business owner might know exactly how much they charge a customer without knowing how much it actually costs to serve that customer.
That gap can become expensive.
Let’s imagine you own a home services company.
You charge $500 for a particular job. The customer agrees to the price, the work gets completed, and you collect the payment.
You might look at that transaction and think you’ve made $500.
But you haven’t.
You’ve generated $500 in revenue.
To understand what you’ve actually earned, you need to account for the costs associated with completing the job.
Consider this example:
What Does It Really Cost to Complete a $500 Job?
A $500 customer payment doesn't mean your business made $500. Labor, materials, transportation, and other delivery costs all reduce the amount available to cover overhead and generate profit. Explore this example to see where the money goes.
These are direct job costs. General overhead, taxes, and other expenses may still need to be covered.
That job contributes $210 toward the business’s overhead and profit.
That’s a 42% contribution margin.
But we’re not finished.
The business still needs to cover its share of insurance, administrative work, software, equipment costs not already included, marketing, and other operating expenses.
Only after accounting for the appropriate costs can you determine the actual profitability of that work.
And there’s another expense business owners frequently overlook.
Their own time.
Let’s say the owner spends two hours preparing an estimate, communicating with the customer, purchasing materials, scheduling the job, handling an unexpected complication, and collecting payment.
If the owner is responsible for those activities, the business is consuming valuable time that could otherwise be spent on sales, management, or other profitable work.
Even when that time doesn’t produce an immediate cash payment, it has an economic cost.
This is particularly important for solo entrepreneurs and small service businesses.
If you’re charging customers for the physical work you perform but failing to account for the time you spend managing each project, you may be underestimating what it actually costs to deliver your service.
And that can lead you to make some pretty bad business decisions.
You might believe you’re profitable when you’re barely covering your expenses.
You might take on additional customers who make your workload heavier without meaningfully improving your financial position.
You might even hire another employee to manage the workload without realizing that the underlying problem is how your existing services are priced and delivered.
Start tracking the full cost of serving a customer.
For each major product or service you offer, identify the costs that are directly attributable to delivering it.
Depending on your business, those costs may include:
- Employee wages and employer payroll taxes.
- Contractor payments.
- Materials, inventory, and supplies.
- Payment processing fees.
- Shipping and delivery.
- Travel time, mileage, and fuel.
- Equipment usage and job-specific rentals.
- Rework, warranty claims, and customer returns.
- Time spent on project management, revisions, and customer communication.
Avoid counting the same expense twice. For example, if a contractor’s labor is already included in your direct project costs, don’t subtract it again elsewhere in your calculation.
Your goal is to understand what each sale contributes toward covering the rest of your business expenses.
Once you have that information, you can begin identifying which customers, products, and services are helping you build a healthier business—and which ones are consuming more resources than you realize.
Underpricing Your Services Can Quietly Destroy Your Profit Margins
Let’s talk about pricing.
It’s one of the most important financial decisions you’ll make as a business owner, and it’s also one of the easiest to get wrong.
I understand why it happens.
When you’re starting a business, you want customers. You want to compete. You want people to choose your company over the alternatives.
So you look at what competitors are charging, consider what customers might be willing to pay, and set your prices accordingly.
Sometimes you even go a little lower because you believe a more affordable price will help you win business.
That strategy can work in certain circumstances.
But there’s a major problem with competing primarily on price.
If your prices don’t adequately cover the cost of delivering your products or services and running your business, more sales can simply mean more work for less money.
Let’s look at a straightforward example.
Imagine you provide a service for $200.
After accounting for direct delivery costs, you have $100 remaining to contribute toward overhead and profit.
Your contribution margin is 50%.
Now imagine you reduce your price by 10% to attract more customers.
Your new price is $180.
If your direct costs remain $100, you now have $80 remaining.
Your contribution margin falls to approximately 44.4%.
That might not sound like a dramatic change.
But look at what happens to the number of sales you need to generate the same contribution.
At $200 per sale, you need 10 sales to generate $1,000 in contribution toward overhead and profit.
At $180 per sale, you need 12.5 sales to generate the same $1,000.
In practical terms, you need 13 whole sales to exceed that target.
That’s a 30% increase in the number of transactions required to generate at least the same contribution.
And remember, this assumes your direct costs remain unchanged.
If fulfilling those additional orders requires more labor, materials, transportation, or customer support, your situation could be even worse.
This is why small pricing decisions deserve serious attention.
A discount that looks minor from the customer’s perspective can have a significant impact on your business’s financial performance.
Calculate your price from your costs, not just your competitors’ prices.
Start by determining what it costs to deliver your product or service.
Then calculate the contribution margin you need to support your overhead, owner compensation where applicable, and desired profit.
For a service business, that might mean evaluating your hourly rate, project pricing, service packages, and minimum job size.
For a retailer, it might mean examining product costs, shipping, payment processing, inventory losses, and other expenses associated with each sale.
For a consultant, it might mean calculating the real amount of time required to deliver a project rather than pricing it based solely on the number of hours spent in a client meeting.
The objective isn’t necessarily to charge the highest price in your market.
It’s to charge a price that reflects the value you provide, the costs you incur, the market you’re serving, and the financial requirements of operating a sustainable business.
And if your current pricing doesn’t work, don’t automatically assume you need to work harder.
You may need to rethink the offer itself.
Not Every Customer Is a Good Customer for Your Business
This might be an uncomfortable conversation, but it’s one worth having.
Not every customer who pays you is equally valuable to your business.
Some customers are easy to work with, pay promptly, understand the scope of your services, and appreciate the value you provide.
Others require constant communication, demand repeated revisions, negotiate every invoice, request additional work without additional payment, and regularly delay decisions.
Both customers might pay the same amount.
But the amount of time and resources required to serve them can be dramatically different.
Let’s imagine two clients who each pay your consulting business $1,500 per month.
Client A provides clear instructions, responds promptly, and requires approximately 10 hours of work each month.
Client B sends frequent last-minute requests, requires multiple rounds of revisions, and consumes approximately 25 hours each month.
At first glance, both clients appear equally valuable because they generate the same revenue.
But let’s assign a hypothetical internal delivery cost of $50 per hour to illustrate the difference.
Client A vs. Client B: Who Is Actually More Profitable?
Two customers can pay the same amount and still deliver dramatically different financial results. Compare how delivery time and service costs affect the contribution each client generates for your business.
Client A
Client B
Customize the Comparison
Change the monthly fees, delivery hours, or internal hourly cost. The graph will update to show how your assumptions affect each client relationship.
Both clients generate $1,500 in revenue.
However, Client A contributes $1,000 toward overhead and profit, while Client B contributes just $250.
Client A generates four times as much contribution toward overhead and profit as Client B in this example.
And that’s before accounting for any other client-specific expenses.
Now imagine you have 10 clients like Client B.
You’re collecting $15,000 per month, but your delivery costs are consuming a substantial portion of that revenue.
You might have built what looks like a successful consulting business while leaving yourself very little room to grow.
Audit your customer relationships.
You don’t need to fire every difficult customer or immediately eliminate a service that has a thin margin.
You do need to understand the financial reality of those relationships.
Start by asking yourself:
- Which customers generate the most contribution toward overhead and profit?
- Which customers consume the most time relative to the revenue they generate?
- Which customers consistently request work outside the agreed scope?
- Which customers pay late and create additional administrative burdens?
- Which customers have the potential to grow into more valuable relationships?
- Which customer relationships are no longer sustainable under their current terms?
Sometimes the solution is a pricing adjustment.
Sometimes it’s a clearer contract, a better-defined scope of work, a more efficient delivery process, or a different service package.
In other situations, you may decide that the relationship no longer makes financial sense.
The important thing is to make that decision based on evidence rather than frustration.
You don’t need the most customers possible. You need a customer base that allows your business to deliver value profitably and sustainably.
Identify Which Products and Services Are Actually Making You Money
If your business offers multiple products or services, there’s a good chance their financial performance varies.
One service might generate substantial revenue with relatively little delivery time.
Another might generate similar revenue but require twice as much labor.
A third might bring in very little money but consume valuable resources that could be directed toward more profitable opportunities.
Without looking at the numbers, it’s easy to treat every product or service as equally valuable.
That can be a mistake.
Imagine a digital marketing agency offering three services:
Which of Your Services Actually Makes Money?
Compare service revenue with the direct cost of delivering the work. A popular service isn't necessarily your most profitable one.
Service A
Example: A premium, higher-priced service
Service B
Example: A lower-priced, labor-intensive service
Compare the Financial Results
These bars compare the monthly contribution from each service after direct delivery costs. The scale updates as you adjust your numbers.
These figures are illustrative and exclude broader overhead.
SEO generates the most contribution in this example, while website design generates less revenue but still contributes a substantial amount.
Social media management, meanwhile, produces $8,000 in monthly revenue but only $2,400 in contribution before overhead.
That doesn’t automatically mean social media management is a bad service.
Perhaps the agency uses it to acquire customers who later purchase higher-value services. Perhaps the delivery process can be improved. Perhaps the service is priced too low.
But it does mean the business owner should investigate before investing more resources into expanding that service.
This is where profitability analysis becomes a powerful strategic tool.
Instead of asking, “Which service generates the most revenue?” you can start asking better questions.
Which service generates the most contribution per hour of delivery time?
Which service has the strongest contribution margin?
Which service creates the most repeat business?
Which service generates qualified leads for other offerings?
Which service requires the least management attention?
Which service has the greatest potential to scale without increasing costs at the same rate?
These questions can reveal opportunities that revenue reports alone will never show you.
Don’t overlook indirect costs.
Direct costs are only part of the picture.
A product or service can generate a healthy contribution margin while still requiring a disproportionate share of management time, customer support, facilities, software, or other overhead.
For that reason, contribution margin and fully allocated profitability should not be treated as interchangeable.
Contribution margin helps you understand how much a sale contributes toward fixed costs and profit.
A more complete profitability analysis also considers how shared operating expenses should be allocated across the products, services, or business units that use those resources.
You don’t necessarily need a complicated accounting system to begin.
Start with a basic breakdown of revenue, direct costs, delivery time, and the major overhead resources each offering consumes.
You can refine your analysis as you learn more.
The objective is to identify where your business creates the most financial value and where changes could produce the greatest improvement.
Discounts and Promotions Might Be Costing You More Than You Realize
Everyone loves a good deal.
Business owners included.
A promotion can attract attention, bring in new customers, increase order volume, and help generate sales during a slower period.
But discounts aren’t automatically profitable just because they increase the number of transactions.
Let’s look at a simple example.
Suppose you sell a product for $100.
The direct cost of producing and fulfilling that product is $60.
You have $40 remaining before overhead and other expenses.
Now you offer a 20% discount.
The customer pays $80, but your direct costs remain $60.
Your contribution falls from $40 to $20.
You’ve cut your contribution per sale in half.
To generate the same $400 contribution you would have earned from 10 full-price sales, you now need 20 discounted sales.
That’s twice as many transactions.
And those additional transactions may require more packaging, shipping, customer service, and administrative work.
The promotion could still be worthwhile if it attracts profitable repeat customers, helps you sell otherwise unsold inventory, or produces other measurable benefits.
But you need to account for those benefits rather than simply assuming they exist.
Measure the actual return on your promotion.
Before launching a discount, answer five questions:
1. What is the contribution on a full-price sale?
Establish your baseline before introducing a promotion.
2. What will the contribution be after the discount?
Calculate the new selling price minus the costs associated with fulfilling the sale.
3. How many additional sales do you need?
Determine how much extra volume is necessary to offset the reduced contribution per transaction.
4. Are you attracting genuinely new customers?
If existing customers would have purchased at full price, you may be discounting sales that would have happened anyway.
5. What happens after the promotion ends?
Look at repeat purchases, customer retention, and whether the promotion creates lasting value.
For advertising campaigns, measure the contribution generated by the additional sales against the promotional and advertising costs.
Don’t confuse revenue attributed to a campaign with profit generated by that campaign.
A promotion that produces $5,000 in additional sales might sound impressive. But if the associated direct costs, discounts, and marketing expenses consume nearly all of that amount, the financial benefit may be minimal.
And if the promotion generates a loss, you need a compelling, measurable reason to accept that loss as an intentional investment.
The bottom line is simple.
A successful promotion isn’t one that generates the most sales. It’s one that produces a worthwhile financial return.
Your Business Can Be Profitable on Paper and Still Run Out of Cash
Here’s another important distinction.
Profitability and cash flow are related, but they aren’t the same thing.
A business can report a profit while struggling to pay its bills.
It can also have money in the bank while operating at a loss.
How does that happen?
Consider a business that completes $20,000 worth of work in October but doesn’t receive payment until November.
Depending on its accounting method, the business may recognize the revenue in October even though the cash hasn’t arrived yet.
Meanwhile, payroll, insurance, materials, and other expenses may still need to be paid in October.
The business could be profitable for the month on an accrual basis and still experience a cash shortage.
The opposite can happen, too.
A business might receive a large advance payment from a customer and have plenty of cash available, even though it hasn’t yet delivered the work or earned all the associated revenue.
That cash can create a misleading sense of financial security if the business owner forgets about the future costs and obligations attached to it.
The U.S. Small Business Administration emphasizes the importance of bookkeeping, financial statements, and cash flow projections when managing a business.
Its business management guidance also explains why tracking money coming in and going out is important when evaluating costs, investments, and operational decisions.
Watch these three numbers together.
Profit: Are your sales generating more revenue than the expenses recognized for the period?
Cash flow: Is money arriving in time to cover your obligations?
Accounts receivable: How much money are customers supposed to pay you, and how long has it been outstanding?
If your business consistently completes work but struggles to collect payment, your cash flow can deteriorate even when the underlying services are profitable.
If you’re buying inventory faster than you’re selling it, your cash can become tied up in products sitting on shelves.
If you’re expanding too quickly, you may need to pay for employees, equipment, and operating expenses before the additional revenue arrives.
That’s why increasing sales isn’t always enough to solve a financial problem.
Sometimes you need better payment terms.
Sometimes you need more disciplined invoicing and collection procedures.
Sometimes you need to reduce the amount of cash tied up in inventory or unnecessary purchases.
And sometimes you need to slow down expansion until the business can comfortably support it.
A healthy business needs a plan for both profitability and cash flow.
Build a Simple Monthly Profitability Scorecard
Let’s turn everything we’ve discussed into something you can actually use.
You don’t need an expensive financial dashboard or an elaborate reporting system to start understanding your business’s financial performance.
You need a consistent way to track the numbers that matter.
I recommend starting with a simple monthly profitability scorecard.
Review it at the same time every month, ideally after your bookkeeping has been reconciled and the relevant expenses have been recorded.
The following measures provide a practical starting point.
Your monthly profitability scorecard
Your Monthly Profitability Scorecard
Track the numbers that matter. Revenue tells you how much money came in. Profitability tells you how much you kept.
1. Enter Your Monthly Numbers
2. Your Profitability Results
3. Where Your Money Goes
Compare monthly revenue, operating expenses, and operating profit. All bars use the same dollar scale so the proportions are easy to understand.
4. Progress Toward Your Profit Goal
Not every metric will apply in exactly the same way to every business.
For example, a retailer may focus heavily on inventory and gross margin, while a consultant may prioritize billable utilization, delivery costs, and contribution per project.
The important thing is to choose measures that reflect how your business actually operates.
Set targets that make sense for your business.
Your profitability scorecard should include targets, not just historical numbers.
If you want to maintain a particular operating margin, record that target and compare your actual results against it.
If you want to reduce the average time it takes customers to pay, track that metric each month.
If a particular service needs to achieve a minimum contribution margin to justify the resources it consumes, establish that threshold and review the results.
Don’t blindly copy industry averages or adopt a target simply because another business owner recommends it.
Profitability varies considerably by industry, business model, location, scale, and stage of development.
Your targets should reflect your own costs, financial obligations, business strategy, and growth objectives.
Also, don’t panic over every monthly fluctuation.
A seasonal business might experience predictable changes in revenue. A company that completes large projects may see uneven monthly results. A business investing in equipment or personnel may experience temporary pressure on its financial performance.
Look for patterns and understand the reasons behind them.
One month of data can reveal a problem. Several months of consistent reporting can help you understand whether that problem is temporary or structural.
The three questions to ask every month
Once you’ve reviewed your scorecard, ask yourself:
- Where did we generate the most profit or contribution this month?
- Where did we spend money without receiving enough financial value in return?
- What is the single most important change we can make next month to improve our results?
That final question matters.
You don’t need to change everything at once.
You need to identify the opportunities that offer the greatest potential improvement and take action.
Over time, those decisions can make a meaningful difference to your business’s financial health.
Five Financial Warning Signs Business Owners Shouldn’t Ignore
How do you know when your business might have a profitability problem?
There isn’t one universal number that applies to every company. But there are several warning signs worth taking seriously.
Warning Sign #1: Revenue Is Increasing, but Profit Isn’t
You’re attracting more customers, selling more products, and generating more revenue.
Yet your profit remains flat or continues to decline.
This can happen when the cost of acquiring customers rises, discounts reduce your margins, labor becomes more expensive, or new sales require more resources than expected.
What to do: Compare your revenue growth with your direct costs, operating expenses, and profit margins over the same period. Identify which costs are growing faster than the revenue they support.
Growth should improve the financial position of your business over time, not simply increase the amount of work you have to manage.
Warning Sign #2: You Have to Borrow Money to Cover Routine Expenses
Using financing to purchase equipment, fund expansion, or invest in a worthwhile opportunity can be a reasonable business decision.
But regularly borrowing money to cover ordinary operating expenses deserves closer attention.
If your business consistently struggles to pay payroll, suppliers, or recurring bills, you may have a cash flow problem, a profitability problem, or both.
What to do: Review your upcoming obligations, payment schedules, receivables, and operating expenses. Determine whether the problem comes from delayed customer payments, insufficient margins, excessive costs, or a combination of factors.
Don’t assume another loan will solve a problem that originates in your underlying business model.
Warning Sign #3: You’re Working More Hours but Taking Home the Same Amount
You’re busier than ever.
You’re answering more calls, completing more projects, and managing more customers.
But your personal financial situation hasn’t improved.
This can indicate that your business is consuming more of your time without generating enough additional profit.
It can also reveal that your pricing doesn’t adequately account for the work required to operate the business.
What to do: Track your working hours alongside revenue and contribution. Calculate how much your business generates per hour of your involvement, then look for opportunities to improve pricing, streamline delivery, or eliminate low-value tasks.
Remember, your time has value even when you’re not receiving an hourly paycheck.
Warning Sign #4: You Don’t Know Which Products or Services Are Profitable
If someone asked you which of your products or services produces the strongest contribution toward overhead and profit, could you answer confidently?
If not, you’re making important business decisions without all the information you need.
Your best-selling service might not be your most profitable. Your largest customer might not be your most valuable. Your most expensive offering might consume so many resources that it produces less financial benefit than a simpler alternative.
What to do: Break down revenue, direct costs, delivery time, and relevant overhead for your major products, services, and customer segments.
Start with your largest revenue sources and the areas where you suspect margins are under pressure.
You don’t need perfect data to begin identifying meaningful patterns.
Warning Sign #5: You Don’t Know How Much Cash You’ll Have Next Month
If you have no clear picture of your upcoming bills, expected customer payments, payroll obligations, and available cash, you’re operating with an important blind spot.
Even a profitable business can experience financial stress when cash arrives too late to cover expenses.
What to do: Create a rolling cash flow forecast that shows expected receipts and payments over the coming weeks and months.
Update it regularly, especially when major invoices, payroll dates, tax obligations, or large purchases are approaching.
You don’t need to predict every transaction perfectly.
You need enough visibility to identify potential shortfalls before they become emergencies.
The common thread connecting all five warning signs is a lack of visibility.
When you don’t understand how money moves through your business, it’s difficult to identify problems early or make confident decisions about what to do next.
The solution begins with better information.
The 30-Minute Profit-Leak Audit: Find Three Opportunities to Improve Your Bottom Line
Now let’s put all of this into practice.
I want to give you a simple exercise you can complete in approximately 30 minutes.
You don’t need to overhaul your accounting system, hire a consultant, or spend an entire weekend studying spreadsheets.
You just need your most recent monthly profit and loss statement, a basic understanding of your business expenses, and a willingness to look honestly at the numbers.
If your bookkeeping isn’t current, use the best available records and clearly mark any estimates. Your findings will be more reliable once you’ve verified the numbers.
The objective is to identify three potential improvements to your bottom line.
Not 30.
Not 15.
Just three worthwhile opportunities you can investigate and act on.
Minutes 0–5: Establish Your Starting Point
Pull together the following information for your most recent completed month:
- Total revenue.
- Direct costs associated with delivering products or services.
- Operating expenses.
- Operating profit, if available.
- Cash balance.
- Outstanding customer invoices.
Write down your total revenue and operating profit.
If your accounting records don’t provide operating profit directly, calculate it using a consistent definition and the relevant expenses.
Next, calculate your operating profit margin:
Operating profit margin = Operating profit ÷ Revenue × 100
For example, if your business generates $20,000 in revenue and $2,000 in operating profit, your operating margin is 10%.
That means the business generates $0.10 in operating profit for every dollar of revenue.
This is your starting point.
Don’t judge the number in isolation. You need to understand your business model and compare your results with your own historical performance and appropriate benchmarks.
Minutes 5–10: Identify Your Five Largest Expenses
Review your expenses and identify the five largest categories.
For a service business, these might include payroll, contractors, advertising, insurance, and software.
For a retail business, inventory purchases, rent, employee wages, shipping, and payment processing may be more relevant.
Now ask three questions about each expense.
Is this expense necessary?
Some costs are essential to operating your business. Others may have accumulated over time without providing much value.
Is this expense producing an adequate return?
Consider whether the expense supports profitable sales, improves efficiency, reduces risk, or serves another meaningful business purpose.
Could I achieve the same result more efficiently?
Perhaps you have duplicate software subscriptions, an underperforming advertising campaign, an expensive process that could be simplified, or a recurring service you no longer need.
Don’t automatically eliminate an expense simply because it’s expensive.
The goal is to identify spending that can be reduced or redirected without undermining the quality of your products, services, or customer experience.
Minutes 10–15: Examine Your Three Biggest Revenue Sources
Identify your three largest products, services, or customer relationships by revenue.
For each one, estimate:
- Revenue generated.
- Direct delivery costs.
- Time required to deliver the work.
- Additional expenses associated with serving the customer or selling the product.
- Contribution toward overhead and profit.
If you don’t have precise figures, start with reasonable estimates and mark them for verification.
Look for offerings that generate substantial revenue but require disproportionate amounts of labor, materials, or management attention.
You may discover that your biggest revenue source isn’t your strongest financial performer.
You may also discover that a smaller offering is consistently generating better contribution with fewer resources.
Either finding can help you make more informed decisions about pricing, staffing, marketing, and future growth.
Minutes 15–20: Audit Your Pricing and Discounts
Now review your current prices and any discounts you’ve offered recently.
Ask yourself:
- Have supplier or labor costs increased since I last set my prices?
- Am I charging for the full scope of work I’m delivering?
- Are customers regularly requesting additional services without additional payment?
- Am I offering discounts without measuring their financial impact?
- Are my minimum prices high enough to justify the resources required to serve each customer?
- Do my prices support the margins I need to sustain the business?
Choose one product or service where your pricing deserves a closer look.
You don’t necessarily need to raise prices immediately.
You might need to redesign the service, establish clearer boundaries, reduce delivery costs, or create a different package.
The important thing is to identify where your current pricing may be preventing you from earning an appropriate return.
Minutes 20–25: Review Your Customer and Marketing Economics
Take a closer look at how you’re acquiring and serving customers.
If you’re investing in advertising, calculate the costs associated with generating new customers and compare them with the contribution those customers generate.
If you run promotions, determine whether they create incremental profitable sales or simply reduce the amount existing customers pay.
If you offer recurring services, look at customer retention, service delivery costs, and the resources required to maintain those relationships.
Ask yourself:
- Which customer relationships contribute the most toward overhead and profit?
- Which marketing channels generate customers who are financially worthwhile to serve?
- Which activities consume time without producing measurable business value?
- Where might a small operational change improve the profitability of an existing customer relationship?
Don’t rely exclusively on revenue attribution or the number of leads generated.
A marketing channel that generates many inexpensive leads may still produce poor financial results if those leads rarely convert into profitable customers.
Likewise, a more expensive channel may deliver a stronger return if it consistently attracts customers who purchase higher-value services and remain with the business longer.
Evaluate your marketing based on the business outcomes that matter.
Minutes 25–30: Choose Your Three Improvements
You’re at the finish line.
You’ve reviewed your financial starting point, examined your largest expenses, evaluated your major revenue sources, looked at pricing, and considered your customer and marketing economics.
Now write down three opportunities you want to investigate or improve.
Use this simple format:
Small Improvements. Stronger Profits.
See how better pricing, lower costs, and stronger revenue can improve your bottom line without relying on guesswork.
1. Your Current Business Performance
Start with your actual monthly figures before testing potential improvements.
2. Test Your Improvement Opportunities
Adjust each percentage to explore a potential improvement scenario. These percentages are assumptions you can change, not industry benchmarks.
3. Your Projected Results
Current vs. Projected Operating Profit
Compare your current operating profit with the profit estimated under your selected improvement assumptions.
These are illustrative examples, not guaranteed results.
The $1,000 associated with collections is potential cash recovery, not necessarily additional profit. The underlying revenue may already have been recognized, and the relevant expenses may already have been recorded.
Similarly, the $300 pricing improvement represents an estimate of additional contribution, not automatically $300 in net profit. The actual impact depends on customer response, delivery costs, and any additional expenses.
That’s why you should distinguish between cost savings, additional contribution, improved cash flow, and additional net profit.
They’re related, but they’re not interchangeable.
Once you’ve selected your three improvements, prioritize them based on their expected financial impact, the effort required, and how confident you are that the change will work.
Then establish a deadline and track the results.
Your objective isn’t to complete a perfect financial analysis in 30 minutes. It’s to identify three concrete opportunities to make your business financially stronger.
Repeat this process monthly.
Over time, you’ll develop a much clearer understanding of where your money is going and which decisions are producing meaningful results.
How to Turn Profitability Into a Growth Strategy
Everything we’ve discussed leads to a bigger question.
Once you understand where your business is making money, what should you do with that information?
This is where profitability stops being an accounting exercise and becomes a strategic advantage.
Let’s say you’ve identified a service that consistently generates strong contribution margins, requires relatively little management attention, and attracts customers who tend to purchase additional services.
That’s potentially a strong candidate for additional investment.
You might decide to improve the marketing around that service, build a referral program, create a more efficient delivery process, or train employees to handle more of the work.
On the other hand, suppose you’ve identified a service that generates significant revenue but consistently consumes excessive time and resources.
You might decide to revise the pricing, narrow the scope of work, improve your processes, or redirect some of your marketing budget toward a more financially attractive offering.
Both decisions can help your business grow more sustainably.
And neither requires you to pursue more sales simply for the sake of increasing revenue.
Build your growth strategy around profitable opportunities.
I recommend thinking about growth in four stages.
First, understand your current financial position.
Establish a reliable baseline for revenue, costs, profit, cash flow, and the performance of your major offerings.
Second, identify your strongest opportunities.
Determine which products, services, customer segments, and marketing channels produce the best financial outcomes.
Third, improve the economics of your existing business.
Address underpricing, inefficient delivery, unnecessary expenses, unprofitable promotions, and customer relationships that consume disproportionate resources.
Fourth, invest in what works.
Once you’ve established that an opportunity can generate an acceptable return, consider directing additional resources toward expanding it.
That might mean increasing advertising spending, hiring employees, improving technology, investing in equipment, or developing a new service.
But before committing additional money, evaluate the expected benefits, costs, risks, and cash requirements.
Growth should be a deliberate investment decision, not an automatic response to a temporary increase in demand.
And remember that your business’s most profitable opportunity may not be its biggest opportunity by revenue.
Sometimes the best move is to improve an existing service.
Sometimes it’s to serve fewer customers more effectively.
Sometimes it’s to increase prices rather than increase workload.
Sometimes it’s to stop doing something that no longer makes financial sense.
The right decision depends on your numbers and your long-term objectives.
Why Financial Visibility Matters More Than Ever
This isn’t just a theoretical exercise.
Small business owners are navigating real financial pressures, and understanding profitability has become especially important in an environment where costs and cash flow remain major concerns.
According to the U.S. Chamber of Commerce’s second-quarter 2026 Small Business Index, released on July 15, 2026, only 16% of surveyed small business owners said they were very comfortable with their current cash flow.
That figure had fallen 15 percentage points from the third quarter of 2025, when 31% reported feeling very comfortable with their cash flow.
The same report found that 57% of surveyed small businesses identified inflation as their biggest concern. Meanwhile, 69% said their businesses were in good health, demonstrating that positive perceptions of overall business health can coexist with financial uncertainty.
These findings come from the Chamber’s quarterly survey, conducted with Ipsos, and describe the experiences and expectations of surveyed business owners rather than every small business in the country. Nevertheless, they highlight an important challenge facing entrepreneurs. (U.S. Chamber of Commerce)
Here’s what I take away from that information.
A business can look healthy from the outside while its owner remains uncertain about the money available to cover upcoming obligations.
Revenue expectations can remain positive even when financial pressure makes it harder to invest confidently in growth.
And when costs rise, businesses need to understand not just how much they’re selling but how much they’re retaining.
That’s why I believe financial visibility should be part of every small business owner’s regular operating routine.
You don’t need to become an accountant.
You don’t need to spend every day buried in spreadsheets.
You do need to understand the basic financial mechanics of your business well enough to recognize problems, evaluate opportunities, and make informed decisions.
The U.S. Small Business Administration recommends maintaining sound bookkeeping practices and understanding your financial statements as part of managing a business.
The IRS also explains that accurate records help business owners monitor performance, prepare financial statements, track expenses, and make informed decisions about their operations. (Small Business Administration)
These aren’t simply administrative tasks.
They’re essential tools for running a business strategically.
Final Thoughts: Stop Measuring Success by How Busy You Are
If there’s one thing I want you to take away from this article, it’s this:
A successful business isn’t simply one that generates more sales. It’s one that turns its sales into sustainable financial results.
You can have a full calendar and an empty bank account.
You can attract new customers every week and still struggle to cover your expenses.
You can double your revenue and discover that your workload has doubled while your financial situation has barely improved.
None of those outcomes automatically means your business is failing.
But they are reasons to take a closer look at how your business operates.
Start by understanding the difference between revenue and profit.
Learn what it actually costs to serve your customers.
Make sure your prices reflect the resources required to deliver your products and services.
Identify which offerings generate the strongest contribution toward overhead and profit.
Evaluate your discounts and marketing campaigns based on their financial results rather than sales figures alone.
And establish a monthly profitability scorecard that helps you recognize problems before they become bigger ones.
Most importantly, don’t assume that every financial challenge can be solved by generating more leads.
Sometimes more customers are exactly what your business needs.
Other times, you need to fix the economics of the business you already have.
Knowing the difference can save you time, protect your margins, and help you make better decisions about where to invest your money.
That’s the kind of strategic thinking that supports sustainable growth.
And it’s something every business owner deserves to understand.
Want to Build a More Profitable Business?
At Stephen Despin Consulting, I believe sustainable business growth starts with understanding what’s working, what’s not, and where your best opportunities are hiding.
Marketing can help you attract customers, generate leads, and increase revenue. But the real objective isn’t to spend more money on marketing or generate sales just to watch the numbers go up.
It’s to build a business that can attract the right customers, deliver meaningful value, manage its resources effectively, and turn growth into lasting results.
That requires looking at the bigger picture.
It means connecting your marketing strategy with your business goals, evaluating the return on your investments, identifying operational opportunities, and making decisions based on evidence rather than guesswork.
If you’re working harder than ever but not seeing the financial results you expected, it may be time to take a closer look at the strategy behind your growth.
Visit StephenDespin.net to learn more about Stephen Despin Consulting and explore how a more strategic approach to marketing and business growth can help you move forward with greater clarity and confidence.
Because at the end of the day, building a successful business isn’t about staying busy.
It’s about building something that works.
Add comment
Comments