

Starting a business is exciting.
There is something incredibly rewarding about taking an idea that exists in your head, putting a name on it, building something around it, and eventually watching someone hand over their hard-earned money because what you created solves a problem for them.
But there is also a side of entrepreneurship that doesn’t fit quite as nicely into the motivational posts we see online.
Building a startup is hard.
Not because entrepreneurs aren’t working hard enough. Not because every struggling founder has a bad idea. And certainly not because there is some secret entrepreneurial formula everyone else knows.
Startups are difficult because, especially in the beginning, you’re trying to solve several enormous problems simultaneously.
You need customers.
You need money.
You need the right offer.
You need people and systems capable of delivering that offer.
And eventually, you need to grow without allowing growth itself to destroy the company you’ve spent all that time building.
The survival data puts that challenge into perspective.
The U.S. Bureau of Labor Statistics has tracked startup survival across multiple economic cycles. Depending on the cohort, only about 50% to 57% of startups were still operating five years after they were created. (Bureau of Labor Statistics)
That doesn’t mean half of entrepreneurs are bad at business.
It means entrepreneurship involves navigating a series of barriers, and those barriers compound.
The good news is that many of them are predictable.
And if you can identify them early enough, you can build around them.
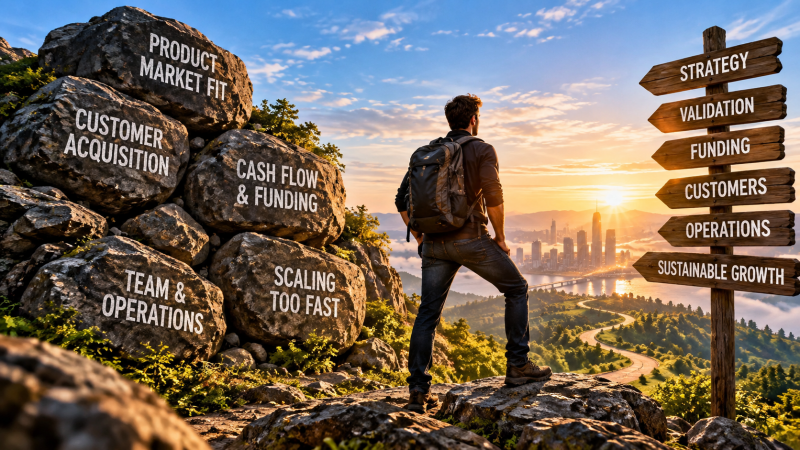
After looking across startup research, federal small-business data, financing trends, and the patterns behind actual startup failures, five barriers consistently stand out.
They are:
- Finding real product-market fit.
- Building predictable customer acquisition and sales.
- Managing cash flow and accessing capital.
- Building the right team, systems, and operational capacity.
- Scaling without growing yourself into failure.
Those five problems are deeply connected.
Let’s break them down.
Barrier #1: Building Something People Actually Want
Every entrepreneur loves their idea.
That’s almost a prerequisite for starting a company.
The problem is that your enthusiasm isn’t market validation.
Your family telling you it’s a great idea isn’t validation.
Your friends liking your Facebook post isn’t validation.
People completing a survey saying they would “probably buy it” isn’t necessarily validation either.
There is a tremendous difference between someone thinking your idea sounds interesting and someone being willing to exchange money for it.
That’s product-market fit.
And failing to find it remains one of the most dangerous startup problems.
CB Insights analyzed hundreds of recent shutdowns among venture-backed startups and found poor product-market fit was cited in 43% of identifiable failures. (CB Insights)
The U.S. Small Business Administration makes essentially the same point from another direction: market research should determine whether demand actually exists, how large the potential market is, who the customer is, what alternatives already exist, and what barriers stand between your company and those customers. (Small Business Administration)
Why founders get this wrong
One of the easiest traps in entrepreneurship is starting with the solution instead of the problem.
You have an idea.
You spend six months building it.
You create the website.
You design the logo.
You order inventory.
You build features.
You spend money advertising it.
Then you finally introduce it to the market and discover something painful:
Nobody really needed it.
Or perhaps people need it, but not badly enough to pay your price.
Maybe another company already solves the problem more conveniently.
Maybe you’re targeting the wrong customer.
Maybe the problem is real but the timing is wrong.
Maybe your solution is too complicated.
Maybe customers love the concept but aren’t willing to change their existing behavior to use it.
That’s why one of the most valuable questions an entrepreneur can ask isn’t:
“Do people like my idea?”
It’s:
“What problem is painful enough that people are already trying to solve it?”
That’s a completely different conversation.
How to overcome it
Start by talking to customers before you start talking at customers.
Interview them.
Listen to how they describe their problems in their own words.
Ask what they’re currently doing to solve the problem.
Ask what they dislike about existing solutions.
Ask what the problem costs them—in money, time, frustration, lost opportunities, or inconvenience.
Then test the smallest viable version of your solution.
You don’t necessarily need the perfect product.
You need evidence.
Can you get 10 customers?
Can you get them to pay?
Will they use the product?
Will they come back?
Will they recommend it?
Can you clearly explain why they bought?
That’s where validation begins.
Your goal in the earliest stage isn’t maximum growth.
It’s maximum learning for the least amount of money possible.
That distinction matters enormously.
Barrier #2: Finding Customers Consistently
You can have the greatest product in your market and still go broke if nobody knows you exist.
This is where many startups hit their second major wall.
They’ve proven that somebody wants what they’re selling.
Now they have to figure out how to find more of those people—consistently, predictably, and profitably.
This isn’t just a startup problem.
According to the Federal Reserve’s 2026 Small Business Credit Survey, reaching customers and growing sales was the most commonly reported operational challenge among employer firms. (Fed Small Business)
Think about that for a second.
Businesses aren’t simply struggling to create products.
They’re struggling to create attention, trust, demand, and sales.
Why this happens
A lot of entrepreneurs confuse marketing activity with marketing strategy.
They create social media accounts.
They boost a few Facebook posts.
They build a website.
They run some Google Ads.
They print business cards.
They send emails.
They try TikTok.
They sponsor something locally.
They post constantly for two weeks.
And eventually they say:
“Marketing doesn’t work.”
The problem usually isn’t that marketing doesn’t work.
The problem is that there was never a defined customer-acquisition system behind the activity.
Successful marketing needs to answer some basic questions.
Who exactly are you trying to reach?
What problem are they trying to solve?
Where do they look for information?
What causes them to trust a company?
What message gets their attention?
What converts that attention into an inquiry?
What converts the inquiry into a sale?
And most importantly:
Can you acquire that customer profitably?
Stop marketing to “everyone”
One of the fastest ways to waste a startup marketing budget is trying to appeal to everybody.
Your target customer shouldn’t be:
“Small businesses.”
That’s enormous.
Neither should it be:
“People who want to get healthy.”
Or:
“Homeowners.”
Or:
“Parents.”
You need to go deeper.
A narrow target makes your messaging stronger because you can speak directly to a specific problem.
Instead of saying:
“We help businesses grow.”
You might say:
“We help independent HVAC companies turn Google searches into booked service calls.”
Suddenly, the customer knows exactly who you’re talking to.
Build a customer-acquisition engine
Your marketing should eventually operate like a system.
Attention → Interest → Trust → Conversion → Retention → Referral
That means your website, search visibility, social content, email marketing, reviews, advertising, sales process, customer experience, and follow-up shouldn’t operate as completely separate activities.
They should reinforce one another.
A potential customer might discover you through Google.
Read an article.
See your reviews.
Visit your social media.
Join your email list.
See another piece of content.
Return to your website.
Request a consultation.
Then become a customer.
That entire journey matters.
And today’s founders also need to think beyond traditional search visibility. Customers increasingly discover businesses through search engines, social platforms, maps, review sites, recommendation systems, and AI-powered answer engines.
Your digital footprint is becoming part of your sales infrastructure.
Measure what matters
Don’t become obsessed with vanity metrics.
Followers are nice.
Impressions are nice.
Likes are nice.
But startups survive on customers.
Track things like:
- Leads generated
- Lead-to-customer conversion rate
- Customer acquisition cost
- Average transaction value
- Repeat purchase rate
- Customer lifetime value
- Churn or retention
- Revenue by acquisition channel
- Return on advertising spend
- Referral volume
If one channel produces 100,000 impressions and two customers while another produces 5,000 impressions and 30 customers, you already know which one deserves more attention.
Marketing decisions should increasingly become resource-allocation decisions based on evidence.
Barrier #3: Cash Flow and Access to Capital
This is the barrier everyone expects.
Money.
But there is an important distinction founders need to understand.
Running out of money is often the symptom, not the disease.
CB Insights’ 2026 analysis of 431 venture-backed companies that shut down since 2023 found that running out of capital appeared in 70% of failures where causes could be identified. But the same research found underlying problems including poor product-market fit, bad timing, and unsustainable unit economics. (CB Insights)
In other words:
A company can raise money and still have a broken business.
Funding doesn’t fix bad economics.
Sometimes it simply allows bad economics to continue longer.
Cash flow isn’t the same thing as profit
This distinction trips up a surprising number of new business owners.
Imagine you invoice a customer $20,000.
Great.
But they aren’t paying you for 60 days.
Meanwhile, payroll is due Friday.
Rent is due next week.
Software subscriptions hit tomorrow.
Your advertising bill is coming.
Your vendors expect payment.
On paper, you’ve generated revenue.
In reality, you can still run out of cash.
That’s why cash-flow management has to become a founder discipline very early.
The Federal Reserve’s 2025 survey found 56% of employer firms reported paying operating expenses as a financial challenge and 51% reported uneven cash flow. (Fed Small Business)
And financing isn’t guaranteed when you need it.
The Fed’s 2026 survey found 60% of employer firms sought financing during the preceding 12 months. Among applicants, 42% received all the financing they sought, 36% received some or most, and 22% received none. (Fed Small Business)
That’s why “we’ll just borrow more money if we need it” isn’t a financial strategy.
Know your numbers before they become emergencies
Every founder should know several numbers almost instinctively.
Monthly burn: How much cash are you spending?
Runway: How long can the company survive at the current burn rate?
Gross margin: After directly delivering the product or service, how much money remains?
Break-even point: How much must you sell before revenue covers expenses?
Accounts receivable: How much money are customers currently owing you?
Customer acquisition cost: How much does acquiring a customer actually cost?
Customer lifetime value: How much gross economic value does that customer create over the relationship?
The SBA specifically recommends calculating startup costs and break-even economics before launch because doing so helps founders estimate profits, establish sales targets, price intelligently, identify missing expenses, and understand how much capital the business will actually require. (Small Business Administration)
The basic break-even formula is beautifully simple:
Fixed Costs ÷ (Price – Variable Cost per Unit) = Break-Even Units
You don’t need an MBA to understand your business.
But you absolutely need to understand your numbers.
Protect your runway
One of the smartest things a startup can do is keep fixed costs flexible for as long as practical.
Don’t hire five people because you hope revenue is coming.
Don’t lease a huge office because it makes the company feel legitimate.
Don’t buy expensive technology because a salesperson convinced you that successful companies use it.
Don’t build infrastructure for 100,000 customers when you currently have 100.
Every dollar you don’t unnecessarily commit today extends the amount of time you have to figure out what works tomorrow.
Capital should buy progress, not appearances.
Barrier #4: Building the Right Team and Operational Systems
Eventually, almost every growing founder discovers an uncomfortable reality:
You become the bottleneck.
In the beginning, doing everything yourself can actually be an advantage.
You’re selling.
You’re marketing.
You’re answering customers.
You’re handling operations.
You’re watching the money.
You’re solving problems.
That proximity gives you incredible insight into the business.
But eventually the very behavior that helped you launch the company begins preventing it from growing.
If every decision requires you…
If every customer problem requires you…
If every sale requires you…
If every approval requires you…
You don’t have a scalable company.
You have a very stressful job that you happen to own.
Hiring doesn’t automatically solve this
The natural reaction is:
“I need employees.”
Maybe.
But hiring the wrong person creates another problem.
Payroll increases immediately.
Productivity doesn’t.
New employees need training, systems, expectations, tools, accountability, and leadership.
That’s why the goal shouldn’t simply be to build a bigger team.
The goal should be to build organizational capacity.
Hire around bottlenecks
Before hiring, ask:
What is currently preventing the company from producing more value?
Maybe you’re spending 15 hours each week on administrative work when those 15 hours could generate substantially more revenue through sales.
That’s a bottleneck.
Maybe customer demand exceeds production capacity.
That’s a bottleneck.
Maybe leads aren’t being followed up with quickly enough.
That’s a bottleneck.
Maybe the founder is approving every $50 purchase.
That’s a bottleneck.
Hire against the constraint.
Don’t hire because you think a company of your size is “supposed” to have a marketing director, operations manager, executive assistant, or vice president.
Titles don’t create capacity.
Systems do.
Document what works
When you discover a repeatable process, document it.
How are new leads handled?
How quickly should customers receive responses?
How are complaints escalated?
How do you onboard clients?
How do you invoice?
How do you approve spending?
How do you publish content?
How do you measure marketing?
How do you hire?
How do you fire?
How do you protect customer data?
How do you ensure quality?
The goal isn’t bureaucracy.
The goal is repeatability.
You want your business to become increasingly capable of producing the same high-quality outcome without reinventing the process every time.
That’s the foundation of scale.
And founders shouldn’t underestimate the value of complementary skills. Startup Genome’s research has found meaningful performance differences associated with team composition; in its earlier research, balanced founding teams combining technical and business capabilities showed stronger fundraising and user growth outcomes and were less likely to scale prematurely than heavily one-sided teams. (Startup Genome)
You don’t necessarily need a cofounder.
But you do need to recognize your blind spots.
The best founders aren’t experts at everything.
They’re good at knowing where they aren’t experts.
Barrier #5: Scaling Too Fast
This one surprises people.
Because growth sounds like the goal.
More customers.
More employees.
More locations.
More products.
More advertising.
More revenue.
More markets.
More everything.
But growth and healthy growth are not the same thing.
Startup Genome’s influential research into thousands of high-growth technology startups found premature scaling in roughly 70% of startups in its dataset. It describes behaviors such as aggressively spending on customer acquisition before product-market fit, hiring large teams too early, overbuilding products, and expanding organizational complexity before the underlying business is ready. (Startup Genome)
That’s the entrepreneurship paradox.
You can fail because you don’t grow.
And you can fail because you grow too quickly.
Imagine this scenario
You own a restaurant.
Your restaurant currently handles 200 orders per day.
Then one of your videos goes viral.
Tomorrow you receive 2,000 orders.
Fantastic, right?
Not necessarily.
Your kitchen can’t handle it.
Orders arrive late.
Food quality drops.
Customers complain.
Employees become overwhelmed.
Refunds explode.
Reviews collapse.
Your reputation takes a beating.
Demand wasn’t the problem.
Capacity was.
The same thing happens in digital companies, service businesses, SaaS startups, agencies, retail businesses, construction companies, and practically every other industry.
Growth multiplies whatever already exists.
If your system is strong, growth multiplies strength.
If your system is broken, growth multiplies dysfunction.
Scale only what has been proven
Before aggressively scaling something, ask:
Does this process already work consistently at a smaller level?
If $1,000 in advertising reliably generates profitable customers, increasing the budget may make sense.
If you have no idea whether the $1,000 generated profitable customers, spending $10,000 isn’t scaling.
It’s gambling.
The same principle applies to hiring.
Don’t scale headcount before you understand workload.
Don’t scale locations before you understand location economics.
Don’t scale inventory without understanding demand.
Don’t scale technology before understanding usage.
Don’t scale customer acquisition before understanding retention.
Don’t scale revenue while ignoring margin.
Watch unit economics
Revenue can be deceptive.
Suppose you sell something for $100.
Everyone celebrates the $100 in revenue.
But what if it costs:
$35 to produce.
$20 to ship and service.
$40 to acquire the customer.
$10 in overhead allocation.
Congratulations.
You generated $100 in revenue while losing $5.
Now imagine scaling from 100 transactions to 100,000.
You didn’t scale a successful business.
You scaled a loss.
That’s why CB Insights’ recent shutdown analysis is particularly useful: unsustainable unit economics appeared in 19% of identifiable startup failures. (CB Insights)
The bigger you become, the faster bad economics can hurt you.
These Five Barriers Are Really One System
Here’s the part I think entrepreneurs sometimes miss.
These aren’t five completely separate problems.
They’re connected.
Think about the chain.
You haven’t found product-market fit.
So customer acquisition becomes expensive.
Because customer acquisition is expensive, cash disappears.
Because cash is tight, you struggle to hire the people you need.
Then you finally get some traction and panic-scale.
You hire too quickly.
Expenses jump.
Operational quality declines.
Customers leave.
Acquisition gets harder again.
Cash tightens.
And suddenly what looks like five different problems is actually one cascading failure.
The opposite is also true.
Find a genuine customer problem.
Build a strong solution.
Develop predictable acquisition.
Understand your numbers.
Build repeatable systems.
Then scale deliberately.
Each successful step strengthens the next one.
Build Your Startup Around Evidence, Not Assumptions
One of the most valuable mindset shifts a founder can make is learning to treat assumptions like hypotheses.
Don’t assume people want your product.
Test it.
Don’t assume your price works.
Test it.
Don’t assume Facebook Ads work.
Measure them.
Don’t assume you need another employee.
Identify the bottleneck.
Don’t assume customers are happy.
Ask them.
Don’t assume you’re profitable.
Know your margins.
Don’t assume you’re ready to scale.
Prove it.
Entrepreneurship will always involve risk.
You cannot spreadsheet every uncertainty out of starting a business.
That’s part of the deal.
But there is an enormous difference between taking calculated risks and operating blindly.
The strongest founders I know aren’t necessarily the people who always have the right answer.
They’re the people willing to discover when their original answer was wrong and change course quickly.
That’s not failure.
That’s entrepreneurship.
A Simple Startup Health Check
If you’re building a startup right now, sit down and answer these questions as candidly as possible:
- Who is our ideal customer?
- What painful problem are we solving for them?
- What evidence proves they’re willing to pay for our solution?
- Where do our best customers currently come from?
- What does it cost to acquire one?
- How much is that customer worth to the business?
- What is our gross margin?
- What is our monthly cash burn?
- How much runway do we have?
- What is our break-even point?
- What is the biggest operational bottleneck today?
- Which processes currently depend entirely on the founder?
- What would break if our customer volume doubled tomorrow?
- What would break if it increased tenfold?
- What are we currently spending money on that isn’t producing measurable value?
If you can’t confidently answer several of those questions, that’s valuable information.
You’ve just identified where to start working.
Startup Success Isn’t About Avoiding Problems
I don’t think the goal of entrepreneurship should ever be to build a company that never encounters problems.
That company doesn’t exist.
The goal is to build an organization capable of recognizing problems early, understanding why they’re happening, and adapting before those problems become existential.
The data shows just how difficult the journey can be. Across different BLS startup cohorts, five-year survival has historically hovered around roughly half. (Bureau of Labor Statistics)
But those statistics aren’t destiny.
They’re a reminder that building a sustainable company requires more than having a great idea.
You need a market.
You need customers.
You need sound economics.
You need operational discipline.
And you need to know when you’re genuinely ready to grow.
The businesses that make it aren’t necessarily the ones that never make mistakes.
They’re often the ones that learn faster than their mistakes can kill them.
And if you’re building something right now, that’s probably the most important lesson of all.
Your first business model won’t be perfect.
Your first marketing strategy won’t be perfect.
Your first pricing model won’t be perfect.
Your first hire won’t always be perfect.
Your first growth plan won’t be perfect.
That’s okay.
Build.
Measure.
Listen.
Adjust.
Improve.
Then do it again.
Because ultimately, the startup journey isn’t about having everything figured out on Day One.
It’s about building a company that gets smarter with every day that follows.
Add comment
Comments